Coming November 2026
Hardcover $25.99 — coming later
THE 12TH FLOOR
THE BOOK
Forget the $300k salary myths. The 12th Floor is a masterclass in everyday financial freedom, tracking how a regular GS-8 federal employee automated a $5 million retirement on a single paycheck. It’s raw, data-backed, and deeply human proof that the savings rate you choose beats the amount you earn.
He grosses about $90,000 a year — with on-call and overtime, not base pay alone. He’ll retire at 57 with $5 million.
No inheritance. No side hustle. No promotion past the middle of the pay scale. Just a spreadsheet kept for 20 years — and the discipline to fund it before he ever saw the money.
The 12th Floor is the receipts: how a GS-8 anesthesia technician — a poor kid from the Philippines who joined the Navy at 17 — turned an ordinary paycheck into a $5 million retirement, one contribution rate at a time.
You don’t need to be a fed to use this. Translate the acronyms and it’s your playbook: TSP = your 401(k) or 403(b). The C Fund = the S&P 500. The 5% match = your 5% match — and skipping it is a pay cut you volunteered for.
- Starting at 5% beats waiting until you can do 30%
- 72 divided by your rate = years to double
- Wealth is what you don’t see
Twelve chapters, twelve rules, and an appendix with every number — year by year, dollar by dollar. Names changed. Numbers real.
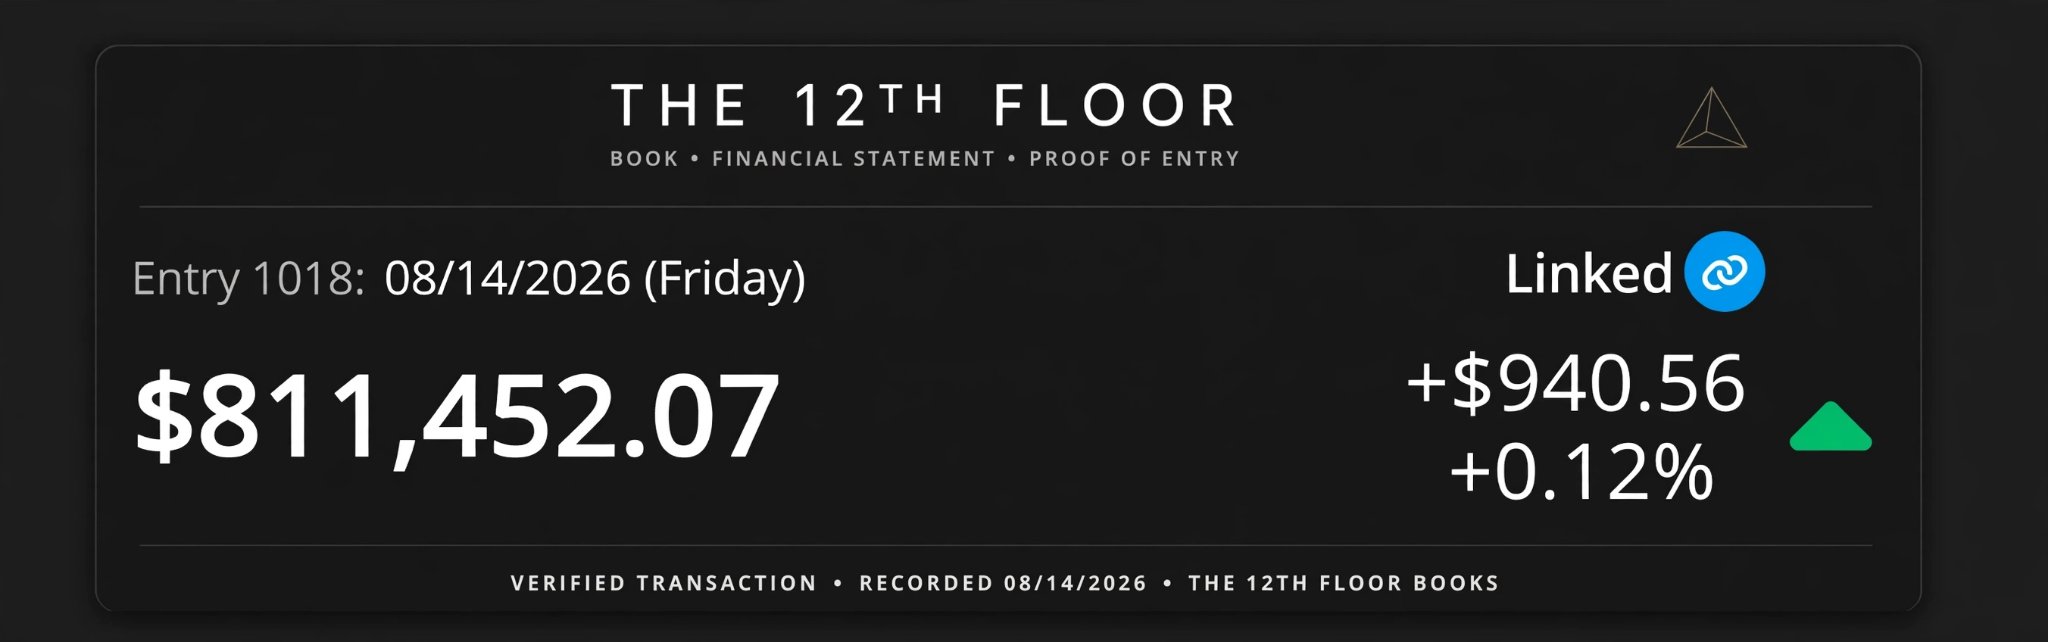
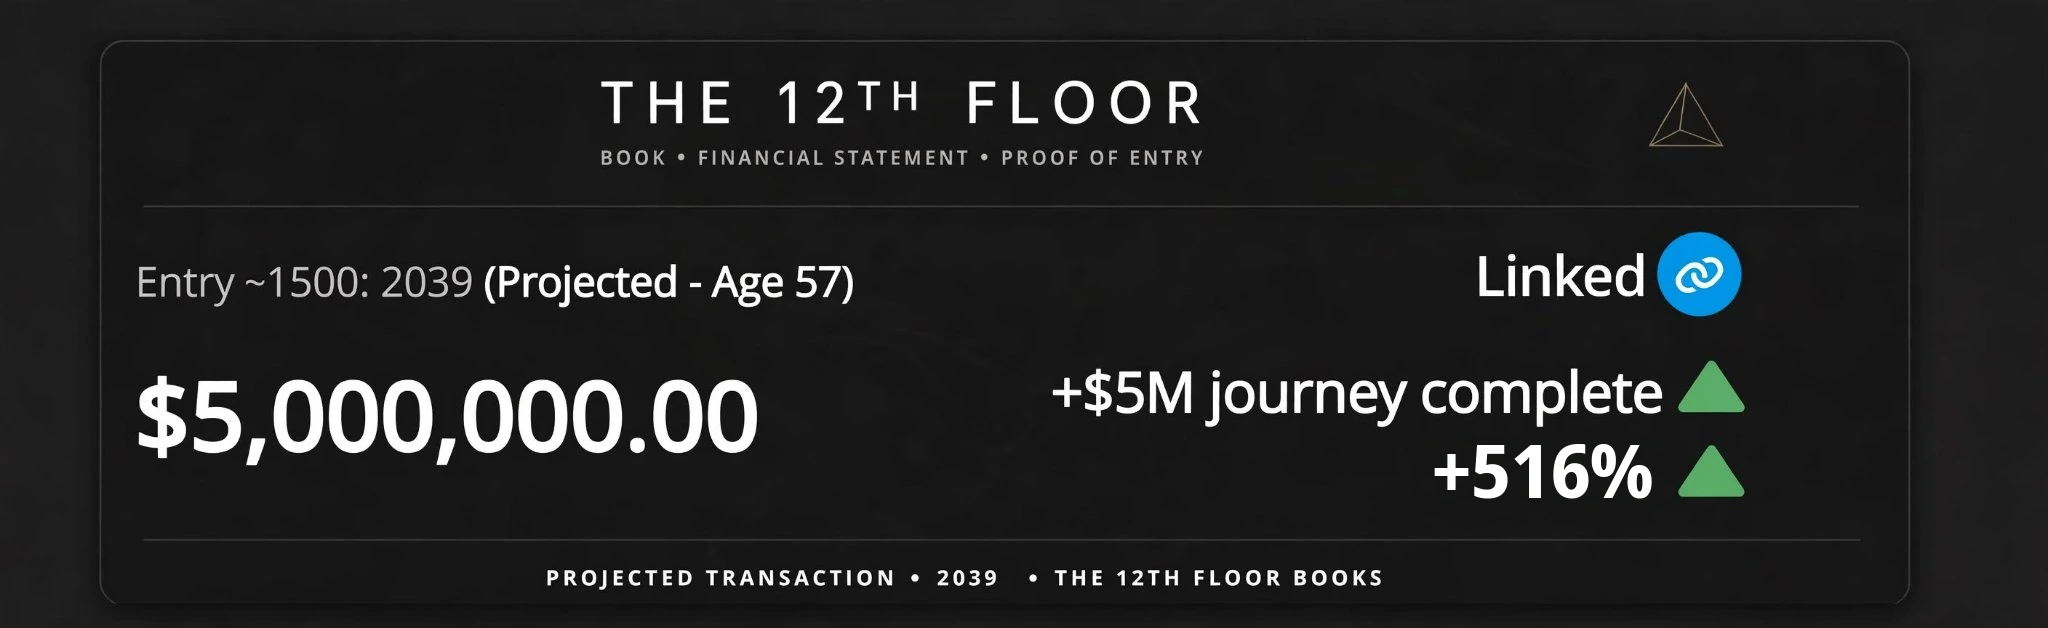
For readers of The Millionaire Next Door and I Will Teach You to Be Rich — the version with receipts.
Read Chapter 1 free — the prologue, ending on Fidelity’s own milestone ladder. Join the launch list below and it’s yours. The rest arrives in November.
FROM THE BOOK
THE 12 RULES OF THE 12TH FLOOR
- Starting at 5.44% beats waiting for 30%. I started in January 2008 at 5.44% and couldn’t max until 2014 — those early dollars got six extra years.
- Raises go to savings before lifestyle. Every GS step and COLA went to TSP before I saw it — lifestyle lag is wealth lead.
- Buy back your military time — $4,090 for 6 years, 9 months. Best check I ever wrote; it added all of it to my pension computation at 57.
- Get the match — 5% free money. Not getting it is a pay cut you volunteered for.
- Add 1% to the TSP/401(k) out of every pay increase of at least 2% — one point to the future, the rest is yours. Anything smaller — a flat 1%, a 1.5% — is COLA money: it all goes to living now. Automatic — no willpower needed.
- Don’t mythologize the lost years — price them. Counting only the years the TSP existed for the military, mine cost about $64k, and the $6,236 seed at ~12% is on track to cancel it when the lines cross in 2028.
- Wealth is what you don’t see: my condo looks like $1,615 a month, but on a $350,000 valuation, a buyer today at 7.625% with 20% down would pay $2,482 a month with HOA for those same four walls. The TSP is what you don’t see.
- Run the numbers, then trust them. 72 divided by rate is years to double — I ran 8/10/12/14% so you can pick your cynicism.
- A plan that survives grief is a real plan. In 2022 I dropped to 20% when Dad passed — I didn’t stop.
- Recovery isn’t a montage. From 2023 to 2026 I rebuilt from 20% to 31% — slow, boring, effective.
- Income vs Wealth. The 401(k) limit is the great equalizer: the doctor making $300,000 gets the exact same $24,500 I do. Income is what you earn; wealth is what you don’t spend.
- Build upward. The cheapest square foot is vertical: $4,000 loft bed vs $633k of added housing costs — same problem, 1/158th the price.
ABOUT THE AUTHOR
Giancarlo Sta Cruz was born in Balanga, Bataan, in the Philippines, and immigrated to the United States in 1998. He enlisted in the U.S. Navy at 17 and served as a Hospital Corpsman — Great Lakes, Okinawa, Quantico — before becoming a federal civilian employee. He has worked at the same San Diego hospitals, in and out of uniform, for most of his adult life.
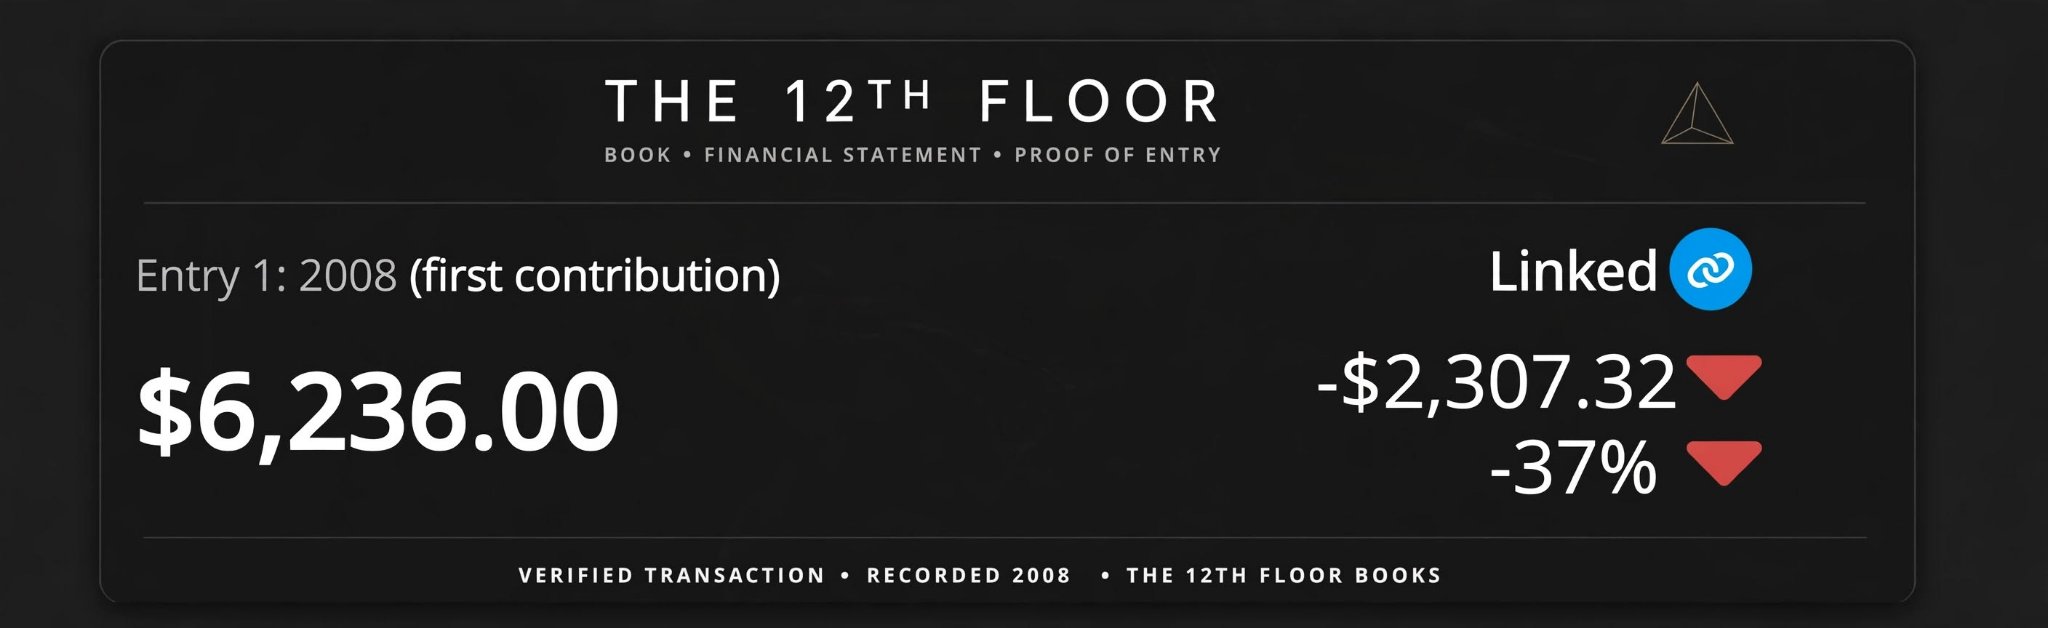
He started his retirement account in 2008 with a $6,236 rollover and a very tiny balance that promptly fell 37%. He kept contributing anyway. Twenty years of statements later, the plan retires him at 57 — and this book shows every line of it.
He lives in San Diego, on the 12th floor, with Pepper, his Boston Terrier — to whom this book is dedicated.
FOR LIBRARIES & BOOKSELLERS
The 12th Floor appears in the San Diego Public Library’s 61st Annual Local Author Exhibit (Central Library, January–February 2027).
Paperback ISBN: 979-8-9822892-0-9 · LCCN: Pending · Publisher: Giancarlo Sta Cruz · 6×9 paperback, $12.99 · Ebook $4.99. A hardcover edition follows.
Press kit, review copies, and event inquiries: [email protected]
GET CHAPTER 1 FREE
Join the launch list and the first chapter is yours — the prologue, ending on Fidelity’s own milestone ladder. Launch notes, once in a while. No noise.